
Financing
Equipment financing.
Loans and leases for new and used equipment. Dealer, auction and private-party purchases.
Who it is for
Contractors, excavators, landscapers, haulers and trades businesses buying equipment they will use in the business. Established businesses and, with stronger credit, newer ones.
What it pays for
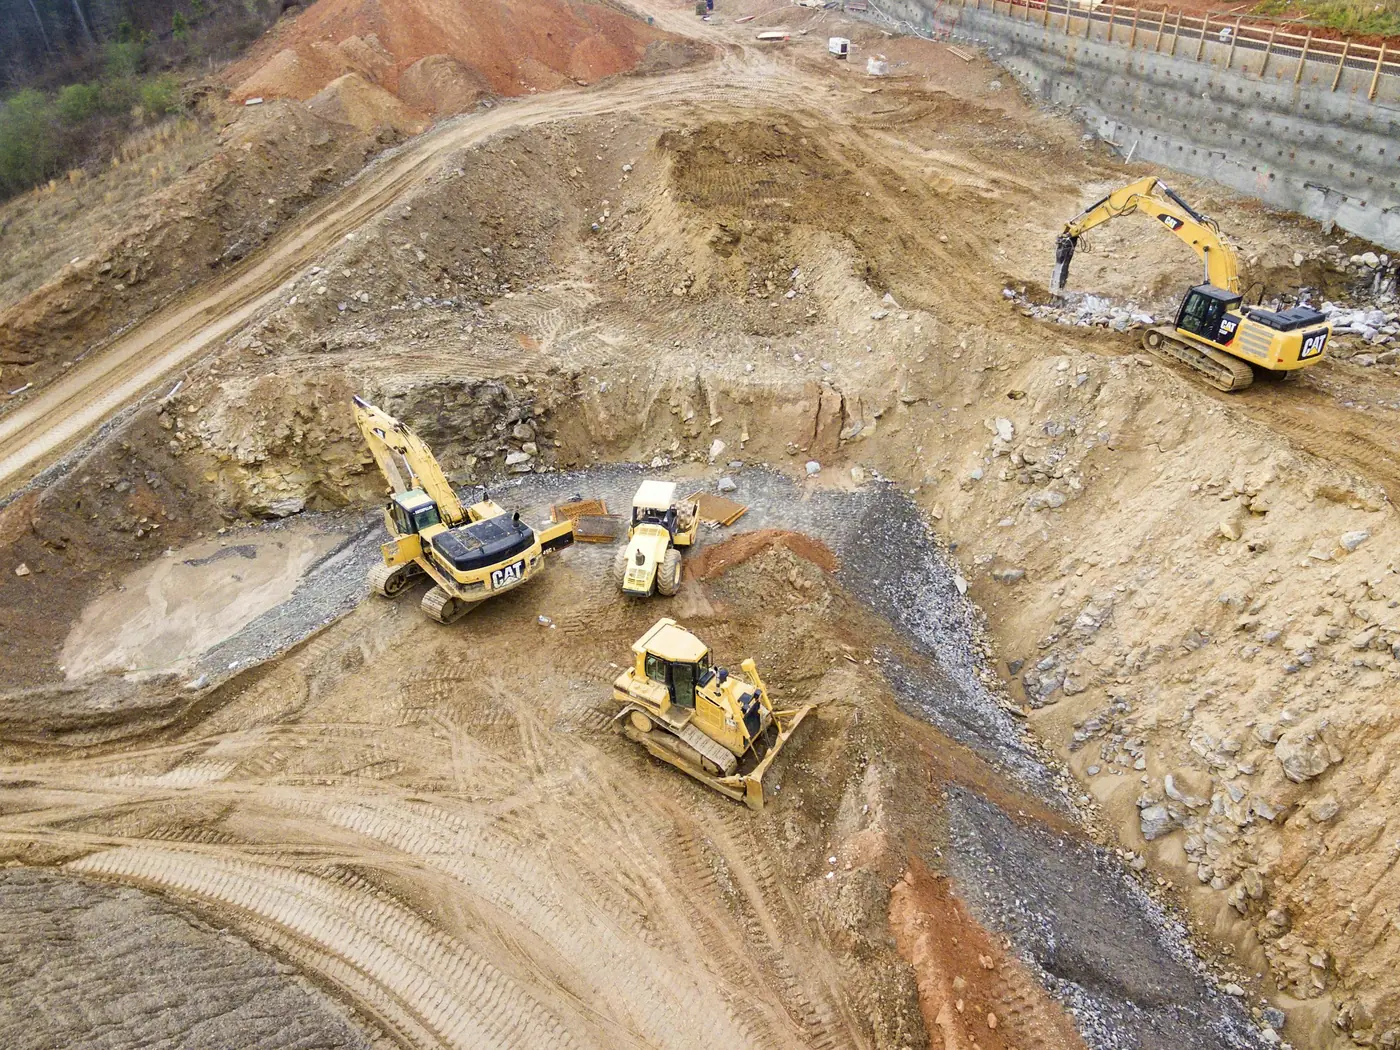
- Skid steers, excavators, loaders, dozers and backhoes
- Mowers, compact tractors and landscaping equipment
- Trailers and attachments
- Used equipment from dealers, auctions and private sellers
- Soft costs such as delivery and installation, with some lenders
Typical requirements
Typical ranges, not promises. Actual terms depend on lender approval.
- Amount
- $10,000 to $500,000
- Term
- 24 to 72 months, sometimes 84 on larger deals
- Time in business
- 2 or more years for the widest options; newer businesses see our startup program
- Personal credit
- All credit profiles considered; 650 and up opens the most lenders
- Down payment
- 0% to 20% depending on credit, time in business and the equipment
- Rate
- Rates depend on credit, time in business and equipment. Typical 8% to 18%.
Documents to have ready
- Completed application
- Quote, invoice or listing for the equipment
- 3 months of business bank statements on most deals over $150,000
- Tax returns or financial statements on larger or more complex deals
How it works
Pre-qualify
Tell us about the equipment and your business. About a minute.
We match you with lenders
Your file goes to lenders in our network that finance your equipment type and credit profile.
Compare offers
We present the terms you qualify for. You choose.
Sign and fund
Sign electronically. The lender pays the seller directly.
Questions
Does pre-qualifying affect my credit?
No. Pre-qualifying with us is not a credit inquiry. A lender runs credit before making a firm offer, and we tell you before your file goes to a lender.
Can I finance used equipment or a private sale?
Yes. Used equipment, auction purchases and private-party sales are common. Depending on age and price, the lender may ask for photos, the serial number or an inspection.
Loan or lease, which one?
With a loan you own the equipment from day one. A $1 buyout lease works almost the same way. A purchase-option lease lowers the monthly payment and leaves a final payment if you want to keep the equipment. The lease vs. buy calculator shows both side by side.
How long does a decision take?
Many deals under $250,000 get a decision within one business day once the file is complete. Larger deals can take a few days.
Do I need a down payment?
Not always. Strong files can finance the full cost. Newer businesses, weaker credit or older equipment usually need 10% to 20% down.
Do you charge a fee to apply?
No. We never charge upfront fees. Our compensation comes from the lender when a deal funds.
What states do you work in?
We actively work with businesses in Alabama, Arizona, Delaware, Kentucky, Mississippi, Montana, New Jersey, New York, Ohio, Oklahoma, Pennsylvania, South Dakota, Washington, West Virginia, Wisconsin and Wyoming. If your business is elsewhere, call us and we will tell you whether we can help.
Related financing
Truck and trailer financing
Semis, dump trucks, box trucks, tow trucks and trailers. New or used, dealer, auction or private sale.
See details →Startup equipment financing
For new businesses with good personal credit and experience in the trade. Startups need stronger credit or a down payment than established businesses, and we say so up front.
See details →Refinancing and sale-leaseback
Lower payments on equipment you are paying off, or turn equipment you own into cash with a sale-leaseback.
See details →Get pre-qualified.
About a minute. No credit inquiry until you choose a lender. We never charge upfront fees.