
Buy the machine now. Let the work pay for it.
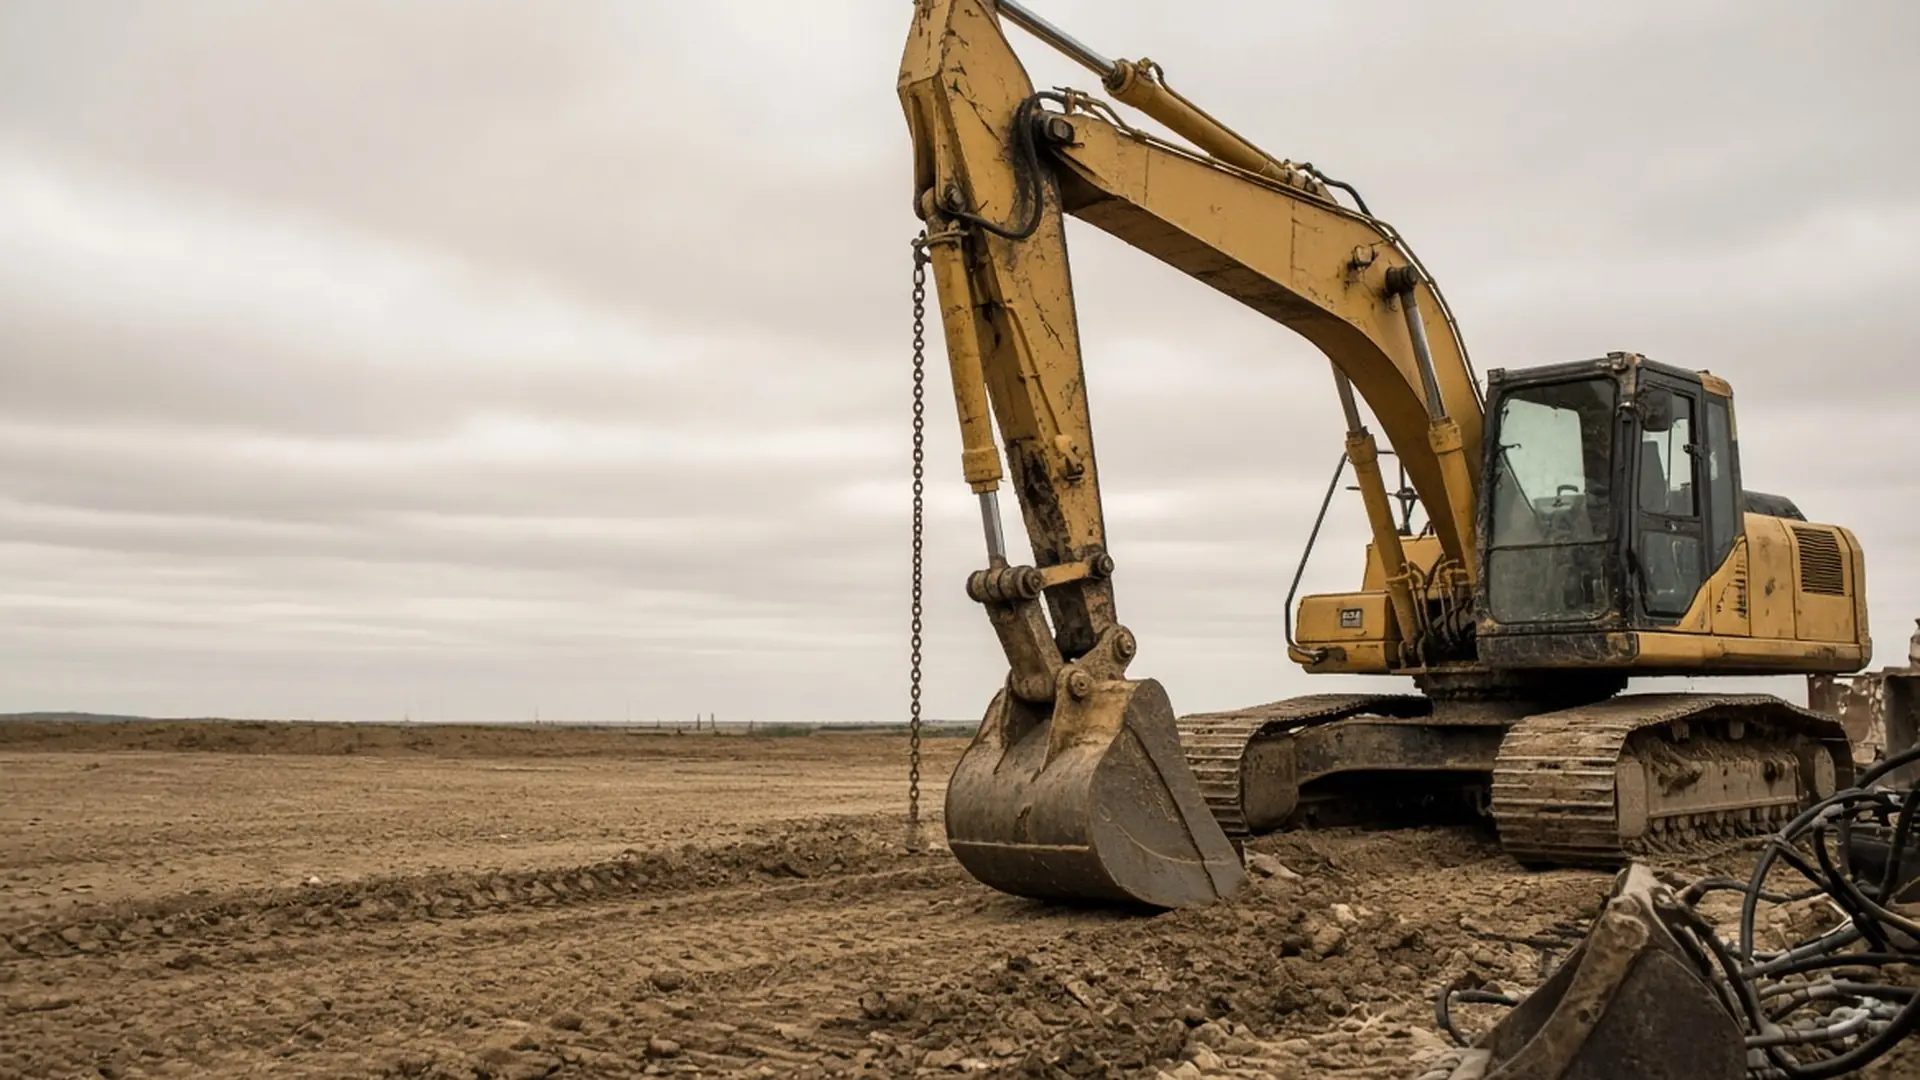
Equipment loans and leases from $10,000 to $500,000 for contractors, truckers, restaurants, medical offices, and shops. New or used, dealer or private sale.
91 days left to put equipment to work for a 2026 tax deduction.
Under Section 179, qualifying new and used equipment that’s bought or financed and placed in service by December 31 can be deducted, up to $2,560,000 for 2026. Approval, delivery, and setup all take time, so the practical deadline comes sooner. Ask your accountant how it applies to your business.
What would it cost per month?
Adjust the numbers to see a typical payment range. This doesn’t check your credit.
Estimated monthly payment
$0/mo
- Estimated rate
- –
- Amount financed
- –
- Total of payments
- –
Estimates only, not an offer of credit. Your rate depends on the lender, your credit, time in business, and the equipment. Rates updated recently.
What we finance
New or used, from a dealer, an auction, or a private seller.
How it works
-
Apply in about two minutes
Tell us what you’re buying and a little about your business. Have the dealer quote or listing handy if you’ve got one.
-
We take it to the right lenders
Your file goes to lenders that finance your kind of equipment and credit profile, so you’re not stuck with one bank’s answer.
-
Pick an offer and get the keys
Compare terms, sign electronically, and the lender pays the seller directly.
One application. Several lenders competing for it.
A bank gives you one answer. As a broker, we send your file to lenders that actually finance your equipment and your credit profile, then bring back the offers worth taking.
- Get approved before you negotiate, and walk into the dealer with financing already lined up.
- Used, auction, and private-party equipment are normal deals here, not exceptions.
- One person handles your file from application to funding, and you can call them directly.
- If a lender says no, you’ll hear why and what would change the answer.
Questions owners ask first
Will applying hurt my credit?
Starting an application doesn’t. A lender has to check credit before it can make a firm offer, and we’ll tell you before your file goes to one.
What do I need to apply?
For most deals under $250,000: this application, the quote or listing for the equipment, and sometimes your last three or four months of business bank statements. Larger deals can also need tax returns or financial statements.
Can I finance used equipment or buy from a private seller?
Yes. Used equipment, auction purchases, and private sales are common. Depending on age and price, the lender may ask for photos, the serial number, or an inspection.
My business is new. Can I still qualify?
Often, yes. Several lenders work with businesses under two years old. Expect a larger down payment or a higher rate than an established business would get.
How fast is the decision?
Many smaller deals get a decision within a business day once the file is complete. Larger or more complex deals can take a few days.
Do I need a down payment?
Not always. Strong files can sometimes finance the full cost. Newer businesses, weaker credit, or older equipment usually need 10 to 20 percent down.
Loan or lease, what’s the difference?
With a loan, you own the equipment from day one. A lease can lower the payment, and at the end you can usually buy it for $1 or its fair market value. When both make sense, we’ll show you both.
Get your approval lined up before the year runs out.
91 days left for 2026 equipment deductions. The application takes about two minutes.